Did You Know Ohio Has A New Distracted Driving Law?

Distracted Driving Law

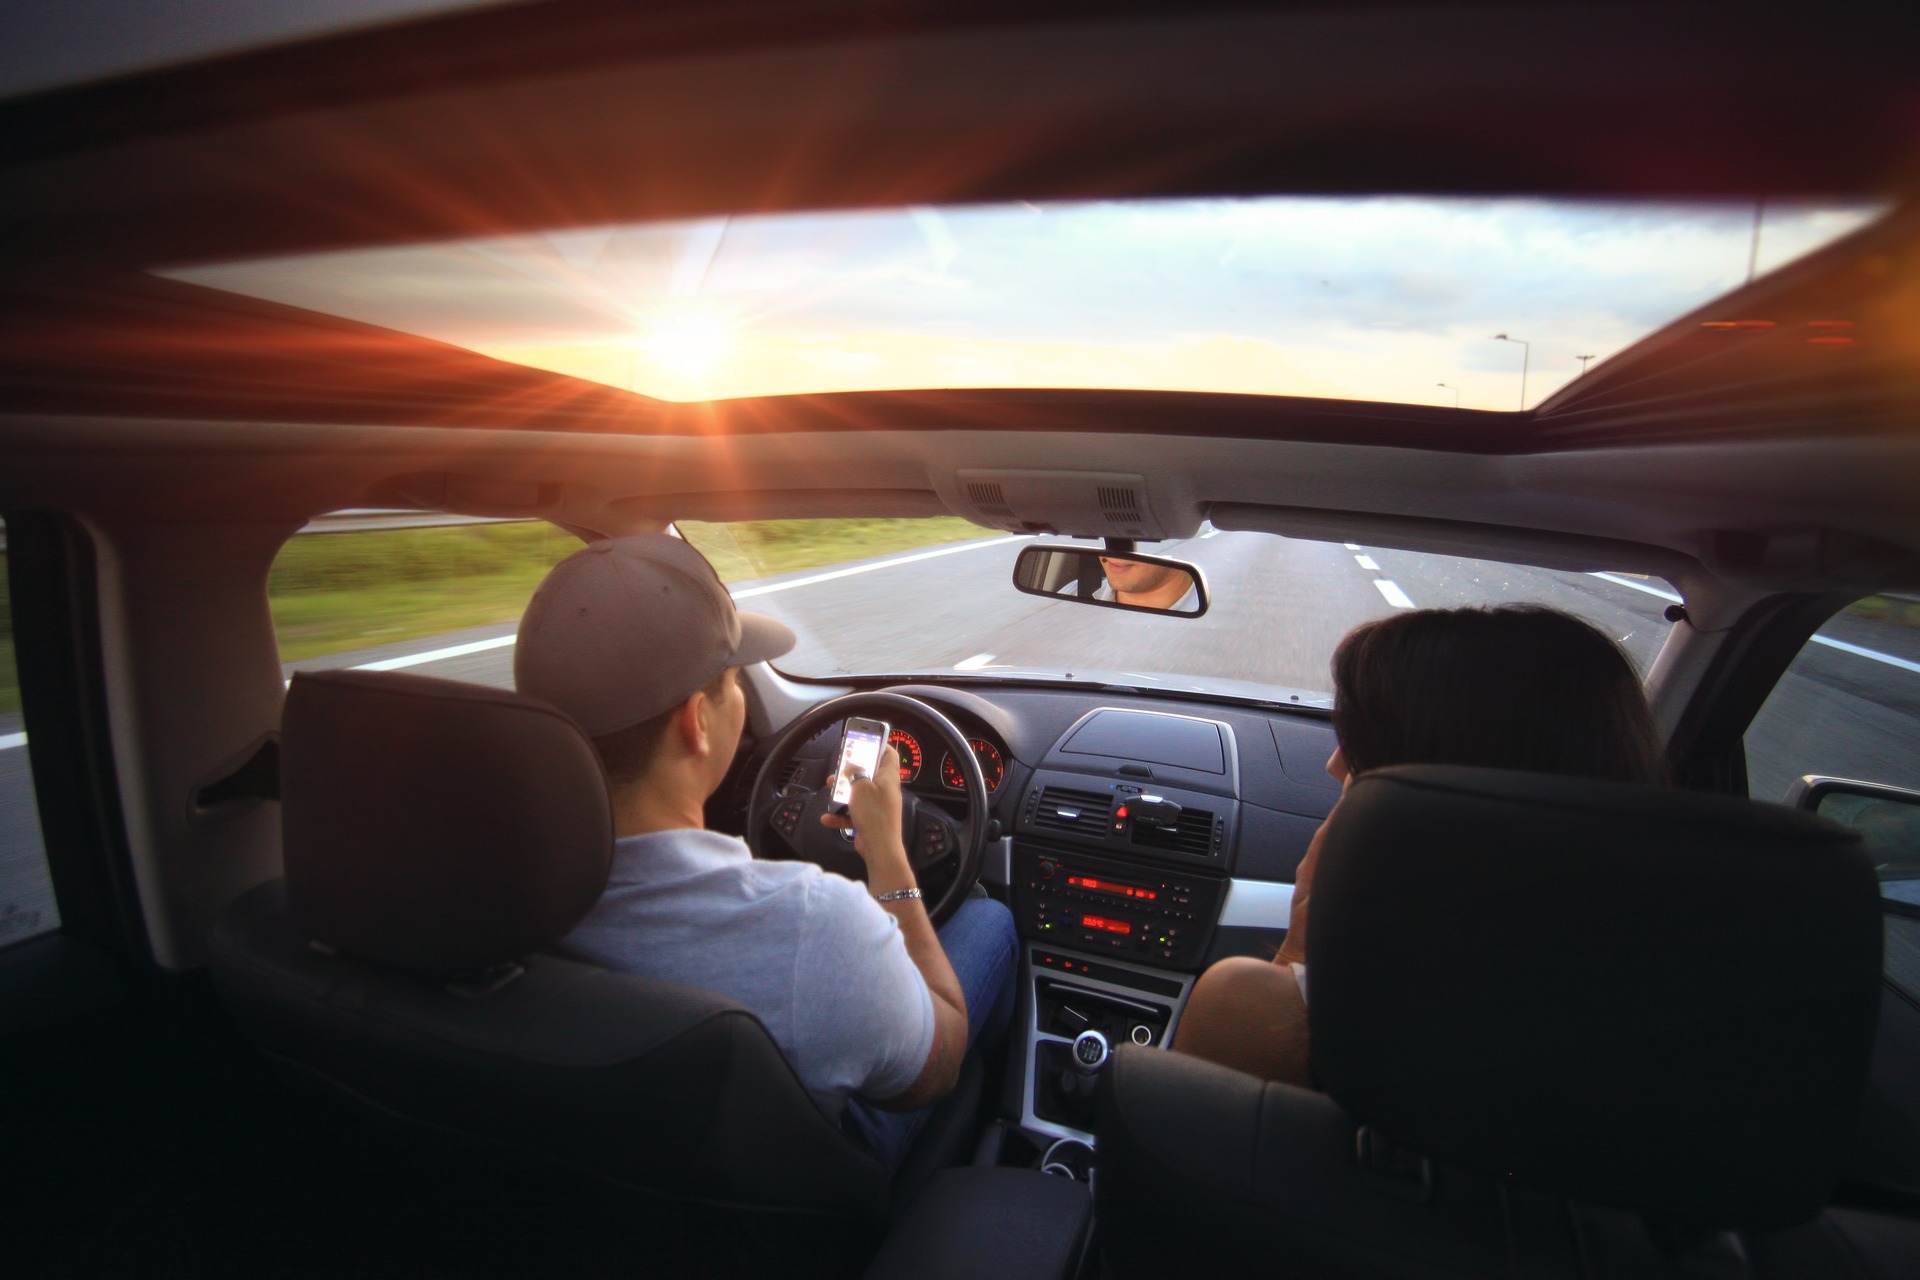
Distracted Driving LawAs of April 4, 2023, it is illegal for drivers in Ohio to use or hold a cell phone or electronic device. This is due to a new distracted driving law. According to the Ohio State Highway Patrol, at least 60,421 crashes and 209 deaths related to distracted driving have occurred in the past five years.

The Ohio State Highway Patrol and local law enforcement will only issue warnings to violators for six months, but beginning Oct. 5, 2023, they will start issuing citations. Members of law enforcement can automatically pull any driver over if they see a phone or other electric device in their hand.

Violations of the Law

Anything that involves using, holding or supporting a device while driving violates the new law. This includes the following actions:

  • Dialing a phone
  • Sending a text message
  • Looking at any social media
  • Video calls
  • Browsing the internet
  • Watching videos
  • Playing games
  • Recording video

The law does not apply to the following:

  • Wearing headphones/earphones
  • Using a device integrated into the vehicle
  • Using the speakerphone feature, as long as the device is not being supported by the driver’s body
  • Streaming audio and navigational apps; they must be set up before embarking, or use a single touch or swipe to activate.

Exceptions to the Law

According to the Ohio Department of Public Safety, there are a few exceptions to the law, which include:

  • Drivers reporting an emergency to law enforcement, fire department, a hospital, a health care provider, or a similar emergency service
  • Drivers holding a phone to their ear only during phone conversations initiated with a single swipe or touch
  • Drivers using a cell phone or other electronic device when stopped at a traffic light or parked on a road or highway during an emergency or road closure
  • First responders (e.g., law enforcement, fire, and EMS) using electronic devices as part of their official duties
  • Utility workers operating a utility vehicle in certain emergency or outage situations
  • Licensed operators using an amateur radio
  • Commercial truck drivers using a mobile data terminal

Penalties

  • First-time offense—A fine of up to $150 and two points assessed to the driver’s license
  • Second offense in a two-year period—A fine up to $250 and three points assessed to the driver’s license
  • Third or more offenses in a two-year period—A fine of up to $500 and four points to the driver’s license, plus a possible 90-day suspension of the driver’s license

However, if the driver completes a distracted driving course, they may be able to reduce their penalties.

For More Information

Drivers can familiarize themselves with the new distracted driving law by reading it in full here. Contact Rinehart, Walters & Danner Insurance Agency to learn how this law may affect you.

Does My Homeowners Insurance Policy Cover Water Damage?

Water Damage

Water damage is one of the most common reasons for homeowners to make an insurance claim. But does homeowners insurance typically cover water damage? The answer depends on the specific policy and the cause of the damage.

To ensure you’re covered for water damage due to water backup, sewer backup and sump pump failure, it is vital to speak with your insurance agent. They can review your current homeowners insurance coverage and help you purchase any necessary endorsements to provide appropriate coverage.

What Causes Water Damage?

Water backup is when water flows back into your home through a drain or a toilet due to a blockage in the main sewer line.

Another cause of water damage that homeowners may encounter is a malfunctioning sump pump. Sump pumps are designed to pump water out of a basement or crawl space, preventing water damage. However, water can flood the home if the sump pump fails. Some homeowners insurance policies may help cover sump pump failures, but it isn’t typically included in a standard policy.

Standard homeowners insurance policies do not typically cover these types of damage. Common reasons for water backups may include the following:

  • Tree roots—When searching for moisture underground, tree roots can enter older or cracked pipes, slowly causing extensive damage or blockages.
  • Aging plumbing systems—As plumbing systems age, they become more susceptible to backups and other problems. Leaky or burst pipes and faulty plumbing fixtures can also cause water damage.
  • Combined pipelines—If your city combines sewer and storm drainage lines, you may experience issues during a storm. Heavy rains can overwhelm the system and create water backup problems in your home.
  • Blockages in the sanitary main—City sewers can also become blocked over time, leading to water backing up into your home.
  • Sump pump failure—A malfunctioning or non-working sump pump could cause extensive damage to your home. Note that while a water backup endorsement may pay for damage caused by sump pump failure, it may not cover the cost of replacing the pump itself.
  • Weather-related issues—Heavy rain, floods, hurricanes and snowstorms can also cause water damage in a home. Water can enter a home through roof leaks, foundation cracks or flooding from nearby bodies of water.
  • Appliance malfunctions—Faulty parts, wear and tear, or poor maintenance can cause serious water damage. Dishwashers, refrigerators, washing machines and water heaters can cause water damage in a home.

Sewer and Drain Backups Cause Devastating Household Damage

Water damage from sewer and drain backups is a common cause of property damage. Water damage and freezing accounted for 19.9% of home insurance claims nationwide in 2020. The average homeowners insurance claim payout for water damage was $11,650 between 2016 and 2020.

How to Help Prevent Water Damage

The following steps can be taken to help prevent water damage:

  • Keep gutters and downspouts clean and free of debris to ensure that rainwater is properly directed away from the foundation of the home.
  • Grade the soil around the foundation to help prevent water from pooling near the home, which can lead to leaks and water damage.
  • Regularly maintain plumbing and sewer lines by having a plumber perform routine inspections to identify potential issues and to clear out any blockages.
  • Avoid flushing inappropriate items down the toilet or pouring grease down the sink, as these can lead to clogs and backups.
  • Install a sump pump or replace an aging sump pump to help prevent basement flooding. Regular testing and maintenance of the sump pump is important to ensure it functions properly.

Water Damage May Cause Mold Damage

Household water damage can lead to mold growth, which can cause serious health problems, especially for people with allergies or weakened immune systems. Mold can grow within 24 to 48 hours of water damage and spread quickly throughout a home.

The cost of mold remediation can be high, ranging from a few thousand dollars to tens of thousands of dollars, depending on the extent of the damage. Unfortunately, mold damage is often not covered by a typical homeowners insurance policy unless caused by a covered peril, such as a burst pipe or accidental overflow of a plumbing fixture.

Homeowners may need additional coverage or endorsements to ensure appropriate coverage for water and sewer backup-related mold damage.

How to Get Coverage for Water Backup

Homeowners can purchase an endorsement that provides water and sewer backup coverage. It’s essential to check with your insurance agent to ensure that you have water backup coverage before a damage-causing incident. The cost of water backup endorsements varies based on the level of coverage and your specific policy.

Making Sure You’re Covered

Reviewing your policy with your agent and purchasing any necessary endorsements for water backup is crucial to ensure you’re covered in a water damage incident. Contact Rinehart, Walters & Danner Insurance Agency today to learn more about your current homeowners policy coverage and available endorsements.

A Nite At The Races To Support The Domestic Violence Shelter

A Nite at The Races

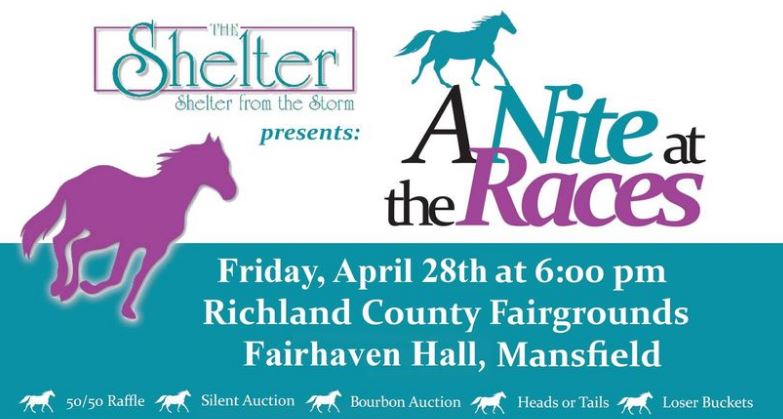
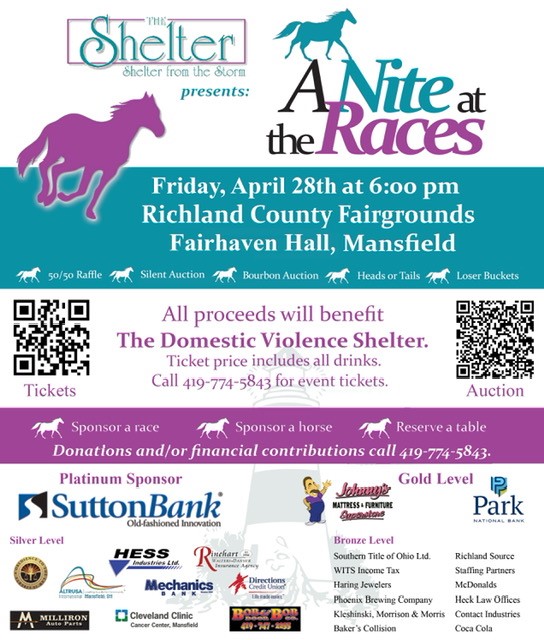
It’s Nite at the Races time!!! One of Richland County’s premier events! Join us for a great night of virtual horse racing, online auction, Bourbon auction, catered meal and drinks. All proceeds benefit the programs of The Shelter. Enjoy a fun night out with dinner and an open bar provided. Plus a chance to win some great auction items, 50/50 raffle and of course horse racing. 

You can find more information and purchase tickets by clicking here. Join us in our support of The Domestic Violence Shelter for a memorable evening.  

Nite at the Races


Severe Thunderstorms; How To Prepare And Stay Safe

Severe Thunderstorms

Severe ThunderstormsSevere thunderstorms produce lightning, which is extremely dangerous. Though lightning fatalities have decreased over the past 30 years, lightning continues to be one of the top three storm-related killers in the United States. In 2014, there were 26 fatalities from lightning. Although most lightning victims survive, people struck by lightning often report a variety of long-term, debilitating symptoms.

Other associated dangers of severe thunderstorms include tornadoes, strong winds, hail and flash flooding. Flash flooding is responsible for more fatalities—more than 140 every year—than any other thunderstorm-associated hazard. Dry thunderstorms that do not produce rain that reaches the ground are most prevalent in the western United States. Falling raindrops evaporate, but lightning can still reach the ground and can start wildfires.

Before a Thunderstorm and Lighting

To prepare for a thunderstorm, you should do the following:

  • Build an emergency kit and make a family communications plan.
  • Remove dead or rotting trees and branches that could fall and cause injury or damage during a severe thunderstorm.
  • Postpone outdoor activities.
  • Remember the 30/30 Lightning Safety Rule: Go indoors if, after seeing lightning, you cannot count to 30 before hearing thunder. Stay indoors for 30 minutes after hearing the last clap of thunder.
  • Secure outdoor objects that could blow away or cause damage.
  • Get inside a home, building or hard top automobile (not a convertible). Although you may be injured if lightning strikes your car, you are much safer inside a vehicle than outside.
  • Remember, rubber-soled shoes and rubber tires provide NO protection from lightning. However, the steel frame of a hard-topped vehicle provides increased protection if you are not touching metal.
  • Shutter windows and secure outside doors. If shutters are not available, close window blinds, shades or curtains.
  • Unplug any electronic equipment before the storm arrives.

Facts about Thunderstorms

  • They may occur singly, in clusters or in lines.
  • A single thunderstorm affecting one location for an extended time can be more severe than other storms.
  • Thunderstorms typically produce heavy rain for a brief period, anywhere from 30 minutes to an hour.
  • Warm, humid conditions are highly favorable for thunderstorm development.
  • About 10 percent of thunderstorms are classified as severe; these storms generally produce hail at least an inch or larger in diameter and have winds of 58 miles per hour or higher. They can also produce tornadoes.

Facts about Lightning

  • Lightning’s unpredictability increases the risk to individuals and property.
  • Lightning often strikes outside of heavy rain and may occur as far as 10 miles away from any rainfall.
  • “Heat lightning” is actually lightning from a thunderstorm too far away for thunder to be heard. However, the storm may be moving in your direction.
  • Most lightning deaths and injuries occur when people are caught outdoors in the summer months during the afternoon and evening.
  • Your chances of being struck by lightning are estimated to be 1 in 600,000, but could be reduced even further by following safety precautions.
  • Lightning strike victims carry no electrical charge and should be attended to immediately.

During Thunderstorms and Lightning

If severe thunderstorms and lightning are occurring in your area, you should do the following:

  • Use a battery-operated National Oceanic and Atmospheric Administration (NOAA) Weather Radio for updates from local officials.
  • Avoid contact with corded phones and devices, including those plugged into electrical outlets for recharging. Cordless and wireless phones not connected to wall outlets are safe to use.
  • Avoid contact with electrical equipment or cords. Unplug appliances and other electrical items, such as computers, and turn off air conditioners. Power surges from lightning can cause serious damage.
  • Avoid contact with plumbing. Do not wash your hands, do not take a shower, do not wash dishes and do not do laundry. Plumbing and bathroom fixtures can conduct electricity.
  • Stay away from windows and doors, and stay off porches.
  • Do not lie on concrete floors and do not lean against concrete walls.
  • Avoid natural lightning rods such as tall, isolated trees in open areas.
  • Avoid hilltops, open fields, the beach and boats on the water.
  • Take shelter in a sturdy building. Avoid isolated sheds or other small structures in open areas.
  • Avoid contact with anything metal, such as tractors, farm equipment, motorcycles, golf carts, golf clubs and bicycles.
  • If you are driving, try to safely exit the roadway and park. Stay in the vehicle and turn on the emergency flashers until the heavy rain ends. Avoid touching metal or other surfaces that conduct electricity in and outside the vehicle.

Lightning Safety When Outdoors

If you are: Then:
In a forest Seek shelter in a low area under a thick growth of small trees.
In an open area Go to a low place such as a ravine or valley. Be alert for flash floods.
On open water Get to land and find shelter immediately.
Anywhere you feel your hair stand on end (which indicates that lightning is about to strike) Squat low to the ground on the balls of your feet. Place your hands over your ears and your head between your knees. Make yourself the smallest target possible and minimize your contact with the ground. DO NOT lie flat on the ground.

After a Thunderstorm or Lighting Strike

If lightning strikes you or someone you know, call 911 for medical assistance as soon as possible. The following are things you should check when you attempt to give aid to a victim of lightning:

  • Breathing – if breathing has stopped, begin mouth-to-mouth resuscitation.
  • Heartbeat – if the heart has stopped, administer CPR.
  • Pulse – if the victim has a pulse and is breathing, look for other possible injuries. Check for burns where the lightning entered and left the body. Be alert for nervous system damage, broken bones and loss of hearing and eyesight.

After the storm passes, remember the following:

  • Never drive through a flooded roadway. Water can damage your vehicle and poses a drowning hazard.
  • Continue to listen to a NOAA Weather Radio or to local radio and television stations for updated information or instructions, as access to roads or some parts of the community may be blocked.
  • Help people who may require special assistance, such as infants, children and the elderly or those with access or functional needs.
  • Stay away from downed power lines and report them immediately.
  • Watch your animals closely. Keep them under your direct control.

In addition to insuring your home, Rinehart, Walters & Danner Insurance Agency is committed to helping you and your loved ones stay safe when disaster strikes. Severe thunderstorms are a regular occurrence in Ohio and everyone should be prepared. If you would like more information on developing a family emergency plan or building a disaster supply kit, please contact us today.

Navigating the Homeowners Insurance Marketplace in 2023, We Can Help

homeowners insurance marketplace

Homeowners insurance continues to be one of the essential types of coverage acquired and maintained by Americans in 2023. However, while these policies may be integral components of homeowners’ insurance portfolios, being common should not be mistaken for uncomplicated. Prospective and current policyholders should remain apprised of recent economic patterns and relevant industry trends to avoid being blindsided by changes in their coverage or costs.

Heading into 2023, several significant conditions are affecting the homeowners insurance market. Inflation continues to have wide-reaching implications for the U.S. economy, and the insurance market is far from immune to these effects. As the cost of building materials used to repair homes and goods replacing destroyed belongings increase, so too must the cost of insurance. In addition, the increasing frequency of natural disasters has led to a recent surge in homeowners insurance claims, culminating in Hurricane Ian inflicting over $67 billion in insured damages last fall.

What to Expect in 2023

Factors that influenced the homeowners insurance marketplace in 2022 are not going to disappear this year. Most policyholders should not be surprised to see their premiums continue to increase, although certain influencers may become less impactful. For example, although construction labor and building material costs continue to affect homeowners insurance costs, recent U.S. Bureau of Labor Statistics show that at least the latter’s increasing prices may be leveling off.

Severe weather events and natural disasters will likely remain significant threats in 2023. With that in mind, increasing insurance premiums, specifically in high-risk areas like southern states, should be expected. Fortunately, homeowners in some areas may enjoy some financial reprieve as government officials take action. For example, in December 2022, the state of Florida passed legislation designed to provide a safety net for insurance companies and stabilize the property insurance market.

5 Tips for Buying Home Insurance in 2023

Amid market trends and global factors mainly outside of the average policyholder’s control, there are still various ways to optimize homeowners insurance coverage and either reduce premiums or minimize increases:

  1. Bundling policies—By combining multiple components of their insurance portfolio under the same broker, such as home, auto and life, homeowners may be privy to discounts as high as 20-25%. Furthermore, bundling coverage can make it easier for policyholders to manage their insurance portfolios and decrease the likelihood of an insurer dropping them in response to an incident.
  2. Improving homes—Upgrading property can help secure lower homeowners insurance prices. Potential improvements may include installing new plumbing or storm shutters, upgrading roofs and adding security or fire protection systems.
  3. Reconsidering home features—Certain additions to your property, such as swimming pools and trampolines, may generate additional risks and exposures. Insurance companies generally must consider such conditions and raise premiums accordingly.
  4. Exploring discounts—Homeowners who have not filed a claim against their policies for an extended period (generally at least three-to-five years) may receive a discount. Even aspects of a homeowner’s life not directly related to their home could earn them lower premiums. For example, many insurance companies may offer discounts for members of the military or certain professions, such as law enforcement officers, firefighters and teachers.
  5. Reassessing coverage—Some homeowners may be able to find lower rates by shopping around for multiple quotes. Altering the details of coverage may also help to keep premiums from increasing. However, policyholders should proceed with caution when adjusting their insurance. For example, increasing deductibles may lower premiums but also mean higher out-of-pocket costs before a policy will render aid.

For most Americans, homeownership is a dream come true. However, like any significant financial investment, a home must be adequately protected by comprehensive insurance. In 2023, many factors must be accounted for while optimizing homeowners insurance policies.

For More Information

Maintaining sufficient coverage while controlling costs can be a difficult task. With that in mind, it’s essential for homeowners to work with a knowledgeable and experienced insurance agent. For more information or help navigating the homeowners insurance marketplace, contact Rinehart, Walters & Danner Insurance Agency today.

5 Tips For How To Navigate The Auto Insurance Marketplace In 2023

auto insurance marketplace

Auto rates increased an average of 9% for drivers in 2022, with 1 in 5 US drivers reporting multiple auto rate increases over the 12-month period, according to Insurify. Unfortunately for drivers and auto insurance consumers, these rate increases are expected to continue in 2023. More accidents, rising medical and litigation costs, more frequent and severe natural disasters and inflation-driven auto repair costs are all expected to contribute to continued auto rate increases in 2023. In fact, US drivers are expected to spend on average $1,895 more in 2023 for the same coverage they had at the end of 2021, said Insurify.

As drivers struggle to find affordable coverage, having an experienced insurance agent on their side will be crucial to help navigate the rapidly changing marketplace. Continue reading for guidance on using an agent to navigate the auto insurance marketplace.

Tips for Auto Insurance Buyers in 2023

Although many of the factors contributing to rising auto rates are out of your control, there are several things you can try to help reduce the cost of your premium increases. Consider the following tips to help keep your auto rates down:

  • Bundle your home and auto insurance. By purchasing multiple insurance policies from the same insurer, you could save up to 25% on your auto premiums. Ask your insurance agent to help you find eligible bundling discounts.
  • Find the right vehicle for your budget. Higher-value vehicles are typically more expensive to repair or replace, leading to higher insurance costs. While several factors may affect your auto premiums, purchasing a vehicle with a lower MSRP could help you find less expensive coverage. Before buying a new-to-you vehicle, ask your insurance agent how much you can expect to pay for auto coverage.
  • Increase your deductible. Raising your insurance deductible is one way to offset rising premium costs, but keep in mind a higher deductible will increase the amount you have to pay out of pocket after an accident. Consult your insurance agent to find out if a higher deductible plan is right for you.
  • Consider a low-mileage plan. Driving fewer than 5,000 miles a year might make you eligible for a low-mileage auto insurance policy. These policies can lower your auto rates. Report your actual mileage to your insurance agent to see if this type of plan could be right for you.
  • Ask your agent to help you find the right policy. Your insurance agent can help you shop around and compare multiple auto insurance quotes to find the right policy for your needs and budget. If you have a good driving record, less expensive insurance options could be available with a new insurance carrier.

We’re Here to Help

As you navigate the auto insurance market in 2023, it’s important to remember you’re not alone. Your insurance agent can help you search for eligible discounts and bring your auto policy into alignment with your coverage needs. Contact Rinehart, Walters & Danner Insurance Agency today to learn how we can help you navigate the challenging auto insurance marketplace.

Want to learn more about Auto Insurance – click here.

Tips to Avoid Trouble When Buying Used Vehicles

Buying Used Vehicles - Rinehart Insurance

Buying used vehicles can be a great way to save a little money. However, make sure to be cautious when purchasing a used vehicle. To avoid purchasing a car with hidden problems, consider the below tips when shopping.

What to look for

  • Excessive wear and tear in the interior, regardless of what the odometer says, is a clue that the car has seen some miles. Look for: Break pedal pad worn through the metal beneath – Driver’s seat outer edge is worn through – Water leaking directly under the floor mats
  • Damp, musty odors are indications of leaks in the windshield, weather stripping or heater core
  • Cars that ride lower in the front as compared to the back indicate worn springs
  • Vehicles that bounce when pushed on indicates worn shocks and struts
  • Tires with worn outer edges from the front end represent the need for an alignment
  • Clanking noises when the vehicle is in gear points towards a problem with the drive shaft universal joints
  • Repainted body panels, Check this by looking at the colors of adjoining panels to see if they match the front fender
  • Motor oil that is not full indicates that the engine may be leaking or burning oil
  • Knocking and ticking sounds that increase as the engine speed increases represent major problems and costly repairs
  • Transmission fluid that is black or brown may indicate internal damage
  • Banging, grinding or squeaking noises indicates a damaged or broken transmission mount

Be Wary of Mileage Tampering

Do not be fooled by the mileage on the odometer. To see if the instruments have been tampered with, look for fingerprints or scratches inside the plastic covering. Mileage numbers that don’t line up properly on the odometer offer another fraud clue. This may be a crude attempt at getting you to buy a vehicle that has far more miles (and problems) than what the low mileage would suggest.

Whether new or used, purchasing a vehicle is an investment. Make sure yours is properly covered by calling our office today to do a policy review.

The Growing Need for Personal Cyber Coverage

personal cyber coverage

personal cyber coverageToday’s society has grown increasingly digital in nature, with many individuals leveraging smart devices within their daily lives. Although this technology can offer various benefits, it can also make individuals more susceptible to cybercrime. Such incidents have steadily become more common and costly. In fact, the FBI reported receiving more than 800,000 complaints regarding cybercrimes in the past year, totaling $4.2 billion in overall expenses.

These findings emphasize how critical it is for individuals to safeguard themselves and their families from cyber events. That’s where personal cyber insurance can help. Typically offered as an endorsement to a homeowners policy, this form of coverage can provide financial protection for losses resulting from a range of cyber incidents—including fraud, identity theft and data breaches. Keep reading to learn more about the growing need for this coverage and the key types of personal cyber insurance available.

The Growing Need for Personal Cyber Coverage

Technology has continued to advance in the past decade, playing a larger role in how individuals live, work, and entertain. A variety of online platforms have given individuals the ability to stream content, communicate with others, shop for goods and make electronic payments at the click of a button. Additionally, smart devices have allowed individuals to upgrade a number of household appliances (e.g., thermostats, fridges, doorbells and security systems). Altogether, this technology has contributed to the growing adoption of the Internet of Things (IoT), which refers to any devices that connect or send information to the internet. Looking ahead, insurance experts anticipate that the average household will possess as many as 50 IoT-capable gadgets by 2023.

While these devices certainly offer several advantages, increased technology utilization also comes with greater cyber vulnerabilities. As technology advances, so do the tactics of cybercriminals—resulting in more frequent and severe cyber events. Here are some of the most common cyber incident scenarios that individuals and their families may encounter:

  • Bank fraud—This form of fraud entails a cybercriminal gaining unauthorized access to an individual’s electronic bank credentials, allowing them to transfer and steal funds from the individual’s account. According to a recent report from NortonLifeLock, cybercriminals steal over $170 billion each year via bank fraud.
  • Identity theft—Such theft refers to a cybercriminal accessing an individual’s personal information (e.g., Social Security number or credit card number) and using it to commit fraud or other crimes under the individual’s name. The Federal Trade Commission confirmed that nearly 1.4 million complaints related to identity theft were filed last year, up 113% from the previous year.
  • Data loss—In the event that an individual’s device gets infected with a virus or other malicious software (also called malware), they face the risk of losing any valuable data stored on that device. Viruses and malware can come from numerous avenues, including harmful websites, dangerous email attachments or infected USB flash drives—thus making data loss a major threat.
  • Extortion—Ransomware incidents have contributed to a substantial rise in cyber extortion over the last few years. These incidents stem from a cybercriminal using malware to compromise an individual’s device (and any data stored on it) and demanding a ransom payment in exchange for restoration. In some cases, the cybercriminal may even threaten to publicly share the individual’s data if they don’t receive payment. According to cybersecurity experts, ransomware incidents have increased 500% since 2018, with the average ransom payment totaling over $300,000.
  • Cyberbullying—While social media platforms allow individuals to connect with others, these platforms can also, unfortunately, be used for negative purposes, such as cyberbullying. This type of bullying includes refers to harassment, threats or other intimidating language that occurs via electronic means. Although anyone can be a victim of cyberbullying, kids and teenagers are particularly vulnerable. The latest data from Pew Research revealed that 59% of teens have experienced cyberbullying.

Considering these risks, it’s clear that individuals can’t afford to ignore cybercrime. In addition to implementing effective cybersecurity practices (e.g., using trusted devices, browsing secure websites, conducting software updates, backing up data, creating unique passwords and knowing how to identify potential scams), having adequate insurance in place is crucial. By investing in personal cyber coverage, individuals can properly protect themselves and their families amid cyber-related losses.

Types of Personal Cyber Coverage

Personal cyber insurance varies between insurers. However, there are a number of key coverage offerings available:

  • Online fraud coverage—This coverage can offer reimbursement for financial losses that may result from the various types of online fraud, such as phishing scams, identity theft or unauthorized banking.
  • Online shopping coverage—Such coverage can help pay for the cost of any goods that were purchased online but arrived damaged upon delivery or didn’t get delivered whatsoever.
  • Identity recovery coverage—This coverage can provide reimbursement for the expenses associated with recovering from an identity theft incident (e.g., rectifying records with banks or other authorities, hiring a consultant to assist with credit restoration and taking unpaid time off from work to recover from the incident).
  • Data restoration coverage—Such coverage can help compensate the cost of having an IT specialist recover a device and restore any data stored on it if the device gets infected with a virus or malware.
  • Data breach coverage—This coverage can offer reimbursement for the necessary notification and recovery services in the event that private, nonbusiness data entrusted to the policyholder becomes lost, stolen or published.
  • Cyber extortion coverage—Such coverage can help pay for the expenses associated with responding to a ransomware event (e.g., consulting an IT specialist to mitigate the extortion attempt and restoring compromised devices or data).
  • Cyberbullying coverage—This coverage can provide reimbursement for the costs that come with recovering from a cyberbullying incident resulting in unlawful harassment or defamation of character. These costs may include psychological counseling services, legal advice, temporary relocation expenses and social media monitoring software. This coverage can also offer protection if an individual or their child faces engages in cyberbullying and faces subsequent legal action from the victim.

Because personal cyber insurance is still a relatively new type of coverage, it is usually only available as an add-on to an existing homeowners policy. Further, certain insurers only provide this coverage as an endorsement for high-value homeowners policies. Yet, some insurers may offer standalone personal cyber coverage. Moving forward, insurance experts expect the personal cyber coverage market to continue growing, allowing for more widely available policy options. In any case, individuals should consult trusted insurance professionals to discuss their specific coverage capabilities.

For further risk management resources and insurance solutions, contact us today.

6 Ways For Your Small Business To Cut Costs

cutting costs

cutting costsEmployers of all sizes are currently searching for ways to reduce expenses and save money in response to the current economic downturn and ongoing labor challenges. Instead of cutting costs randomly or conducting unnecessary layoffs, successful organizations tend to optimize their resources by identifying areas where they can reduce expenses without compromising productivity or future growth. While cutting costs is essential for any organization, it’s especially important for small businesses since they tend to have fewer resources than larger employers.

This article outlines six tips to help small businesses effectively cut costs.

1.       Invest in New Technology

Adopting new technology can bolster efficiency and create savings for small businesses. Investing in technology can help reduce costs by streamlining operations and allowing small businesses to operate more efficiently. Technology enables employers to improve or even automate manual and error-prone tasks. Examples of cost-saving technology include the following:

  • Customer relationship management software
  • HR management or information systems
  • Digital communication
  • Virtual recruiting services
  • Low-code solutions
  • Artificial intelligence
  • People analytics technology
  • Learning and development software

Additionally, many small businesses are turning to open-source software alternatives as a cost-effective alternative to brand-name software applications.

2.       Strengthen Employee Retention

Prioritizing employee retention can be one of the most effective cost-cutting strategies for small businesses. Replacing workers is often extremely expensive. Employee turnover not only increases an organzation’s recruiting and training costs but also usually results in decreased productivity, lost proficiency and reduced profits.

Small businesses can strengthen employee retention with the following strategies:

  • Provide opportunities for career development and advancement.
  • Offer benefits to meet workers’ evolving needs.
  • Improve employee engagement by encouraging employee feedback, providing flexibility and strengthening workplace efficiency.
  • Bolster workplace culture through public recognition and reward programs.
  • Be transparent when communicating with employees to help them understand important decisions and establish opportunities for two-way feedback.

3.       Manage Health Care Costs

It’s not a secret that employer health care costs are rising. Finding cost-effective solutions is vital for small businesses to maintain affordable benefits and reduce costs. Solutions may include reevaluating plan designs and offerings, directing employees to cost-effective services and improving employee health care literacy. Employers can leverage their relationship with their insurance brokers to explore cost-saving solutions, like obtaining details on organizational health care spending and educating employees on shopping for health care services. By adopting several cost-cutting strategies, small businesses can better manage health care costs without sacrificing employees’ needs.

4.       Embrace Outsourcing

While performing tasks in-house can often be cost-effective, there are instances when outsourcing nonessential tasks can be more economical. Manual, time-consuming tasks—such as payroll and benefits administration—may be better suited for outsourcing for some organizations. Outsourcing these kinds of tasks can enable employees to focus on more important responsibilities that have a greater and more direct impact on a small business’s bottom line and future growth.

5.       Adopt Flexible Work Arrangements

The expense of having a physical workspace can add up. Each month, employers must pay rent, utilities, cleaning costs and other expenses. While these expenses are often unavoidable, some small businesses are transitioning to home-based businesses or remote and hybrid work arrangements to cut costs. These solutions may not be suitable for all industries or job positions, but small businesses of all kinds can explore ways to offer flexible scheduling and improve benefits, like enhanced leave and paid time off, to lower overhead expenses. If converting to a home-based business or going remote isn’t possible, employers can consider downsizing their facilities to reduce their rent and utility bills. Small businesses can also explore other alternatives, such as co-working arrangements and renegotiating their leases, to reduce rent.

6.       Review Expenses

Poor cash flow can strain and even jeopardize an organization’s longevity. Reviewing expenses regularly can be an effective way to reduce and eliminate unnecessary costs. As part of the review process, employers can negotiate with providers, suppliers and vendors, such as banks and landlords, to potentially defer payments, reduce fees, improve rates and receive additional services to help during difficult times. By establishing and fostering relationships with these individuals and entities, organizations can cultivate allies and acquire strategic partners, which can pay dividends by creating cost-savings solutions and opportunities.

Summary

Effective strategies for cutting costs will likely vary for each small business. However, by planning properly and understanding effective cost-cutting approaches, small businesses can identify and reduce the costs that will have the most impact on their organizations. This can help small businesses bolster their financial stability, optimize their resources and position themselves for future growth.

For more workplace resources, contact Rinehart, Walters & Danner Insurance Agency today.
6 Tips For Better Brain Health

brain health

brain healthA brief lapse in memory, such as misplacing your wallet or forgetting a birthday, is often associated with being overly busy or having an excessive amount of stress. In fact, memory loss is a common part of aging. What can be problematic is when the episodes of forgetfulness increase and intensify into a more severe problem, such as mild cognitive impairment or even Alzheimer’s disease.

This is why taking care of your brain health is essential. There are small daily efforts you can make to slow memory decline. Read on for six tips about taking care of your brain health.

1) Exercise Daily

Physically active people are less likely to experience a decline in their mental function, according to the Mayo Clinic. The increased blood flow to the brain during exercise aids the natural brain connections that occur during aging. A simple routine of 30 minutes of physical activity daily can help boost your brain health. Try choosing an activity that will increase your heart rate, such as hiking, playing tennis or biking.

2) Eat a Balanced Diet

A balanced diet not only helps physical health but cognitive functions as well. Try to incorporate foods high in monounsaturated fats, polyunsaturated fats and omega-3 fatty acids. These foods can include salmon, nuts and avocados, for example. It’s also important to avoid foods high in trans and saturated fats, such as processed foods and fatty cuts of beef.

3) Get a Good Night’s Sleep

Sleep plays a vital role in overall health, including brain health. To get a good night’s sleep, you should aim for seven to eight consecutive hours of rest per night. This gives the brain a chance to detoxify and relax after each day, which is critical for a healthy brain and memory.

A lack of sleep can be a detriment to your brain health. If you’re having trouble sleeping, it can be helpful to reach out to your doctor. 

4) Participate in Social Activities

Regular social interactions can help decrease memory loss. This can especially be important if you live alone or work remotely. A simple way to incorporate social interaction into your daily life is to connect with loved ones such as family and friends. If you have time in your evenings, this could be a good opportunity to try a new hobby or class within your community.

5) Activate Your Brain

The more mentally stimulated you are, the better your brain’s overall function will be. To engage in mental stimulation, you can participate in activities such as reading, brain games, painting and puzzles. If you’re looking for where to start with brain-stimulating exercises, reach out to your doctor for recommended resources.

6) Receive Regular Check-ups

Certain health factors, such as artery and vein health, are critical to brain health and function. By going to regular check-ups, you’re able to get your blood pressure, blood sugar and cholesterol checked. Your doctor can tell you if your these and other numbers are in a healthy range. If not, they can provide care to help you get your numbers in a healthy range.

Conclusion

Brain health significantly impacts your memory and cognitive function. Practicing these six habits can positively impact your brain’s health. If you have further questions about how to better the health of your brain, reach out to your doctor for more information.